
Quarterly Business Insights Q2 2026
NI CHAMBER IN PARTNERSHIP WITH QUEEN'S UNIVERSITYNorthern Ireland remains one of the strongest-performing UK regions in Q2 2026, continuing to invest and hire even as the rest of the UK pulls back. Northern Ireland is positive on both investment and recruitment activity where UK-wide balances have turned negative. Beyond this, however, growth is increasingly narrow and uneven. Most indicators remain in positive territory, meaning slightly more firms report improvement than deterioration, but the margins are often narrow, and activity is increasingly reliant on hiring, investment and exports rather than domestic demand.
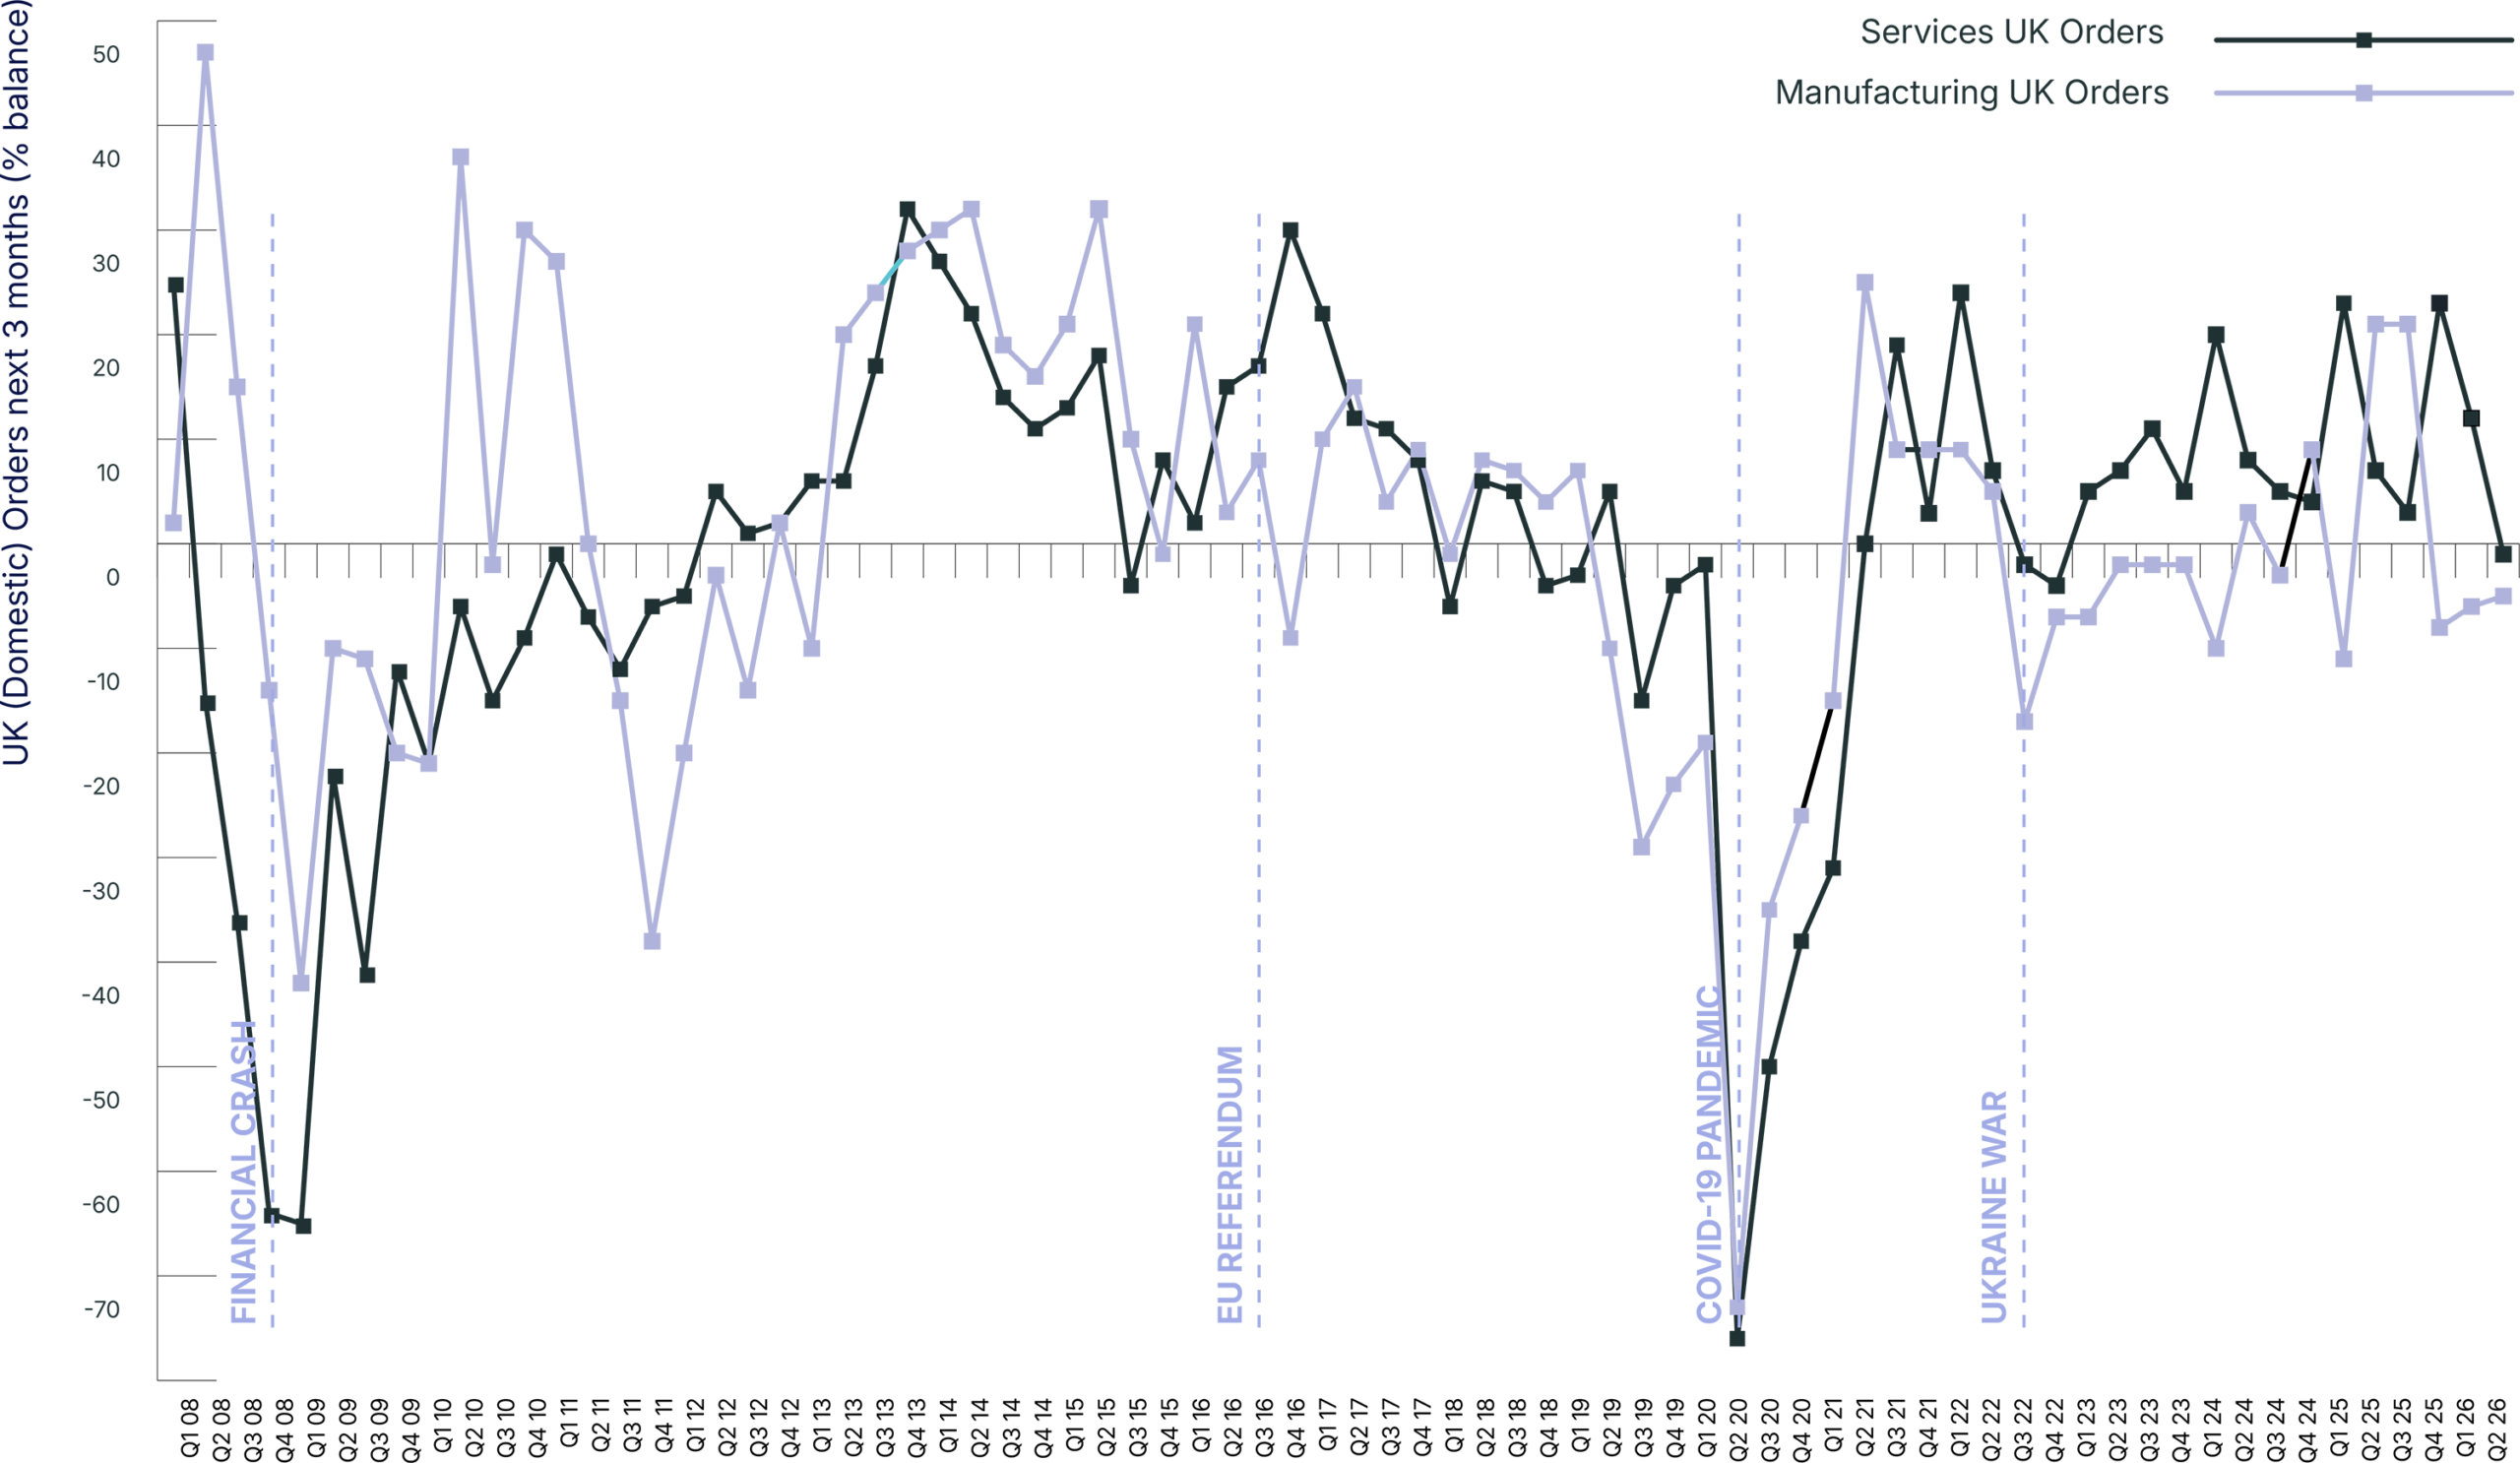
Domestic demand conditions remain the main weakness and there are early signs of softening. Services domestic (UK) orders have flattened to around zero, having been positive in each of the previous twelve quarters. It is a modest move, but one worth watching after a sustained positive run. Manufacturing domestic demand remains negative on both sales and orders. Exports, by contrast, are a relative strength this quarter: Northern Ireland is positive on export sales in both sectors and on services export orders, while UK-wide export balances are negative across the board.
Cost pressures remain embedded and in manufacturing, have re-intensified. Price expectations have risen again to their highest in over a year, driven by renewed pressure from fuel and raw materials, while labour costs remain the dominant pressure across both sectors.
Recruitment activity remains high but is not translating into stronger employment growth. Hiring appears to be increasingly focused on replacement rather than expansion, reflecting ongoing skills shortages and some of the tightest labour market conditions in the UK. Investment remains positive and ahead of most UK regions, though cautious, with no clear sign of acceleration. Cashflow remains weak and volatile.
Confidence has diverged this quarter. In services it has held broadly steady, while in manufacturing it has weakened materially, with profitability expectations declining for a sixth consecutive quarter to at or below zero. This divergence is a defining feature of the Q2 2026 picture.
Taken together, the Q2 2026 findings point to an economy that continues to hold up and outperform most UK regions, but with growth resting on exports, investment and hiring rather than domestic demand, and with manufacturing confidence and persistent cost and labour pressures the main areas of concern.
% balance of firms reporting improved domestic (UK) orders (next 3 months)
Manufacturing
Northern Ireland’s manufacturing sector continues to perform relatively well compared to other UK regions, ranking among the strongest on investment and recruitment activity, but conditions are mixed, and confidence has weakened. Around seven of the eleven key balances are positive, meaning more firms are reporting growth than decline, though domestic sales, orders, cashflow and profitability confidence all sit below zero. Strength is concentrated in jobs and investment, while domestic demand and confidence are the clear weak points.
UK order balances remain negative this quarter, pointing to continued weakness in domestic demand, with domestic sales in the lower half of the UK regional range. Export sales are outperforming, holding clearly positive against a negative UK balance, though export orders have flattened.
Confidence has weakened materially. Profitability expectations have declined for a sixth consecutive quarter and now sit at or below zero, while turnover confidence has eased sharply, pointing to a deteriorating outlook. Price expectations have risen again to their highest in over a year, reflecting renewed input-cost pressure from fuel and raw materials.
Recruitment activity is among the strongest of any UK region, but is increasingly focused on replacement rather than expansion, with recruitment difficulties among the most acute in the UK. Cashflow remains weak and volatile. Investment intentions remain positive and ahead of most regions, though cautious.
Overall, manufacturers continue to face a combination of weak demand, rising costs and weakening confidence, with labour costs remaining the dominant pressure. Activity is being maintained through investment and hiring, but the outlook has softened.
Services
Northern Ireland’s services sector is among the strongest performing of any UK region in Q2 2026, remaining positive across almost every indicator and stronger than manufacturing. Almost all key balances are positive, ten of the eleven, with only domestic orders marginally below zero, so across the sector far more firms are reporting growth than decline.
Domestic demand is holding up better than across the UK as a whole, with sales modestly positive and orders around zero. Export demand is a particular strength, staying positive on both sales and orders while national balances remain negative. Employment and hiring intentions are among the strongest in the survey.
Investment and cashflow are also holding up well, remaining positive where the UK as a whole has turned negative. Confidence has held broadly steady, with turnover and profitability expectations remaining positive rather than easing as they have in manufacturing. Price pressures were largely stable this quarter.
Overall, services continue to support economic activity and outperform other regions, but the main constraint is capacity: recruitment activity remains high but is not fully converting into employment growth, held back by elevated recruitment difficulties and by labour, tax and overhead costs.
Recruitment
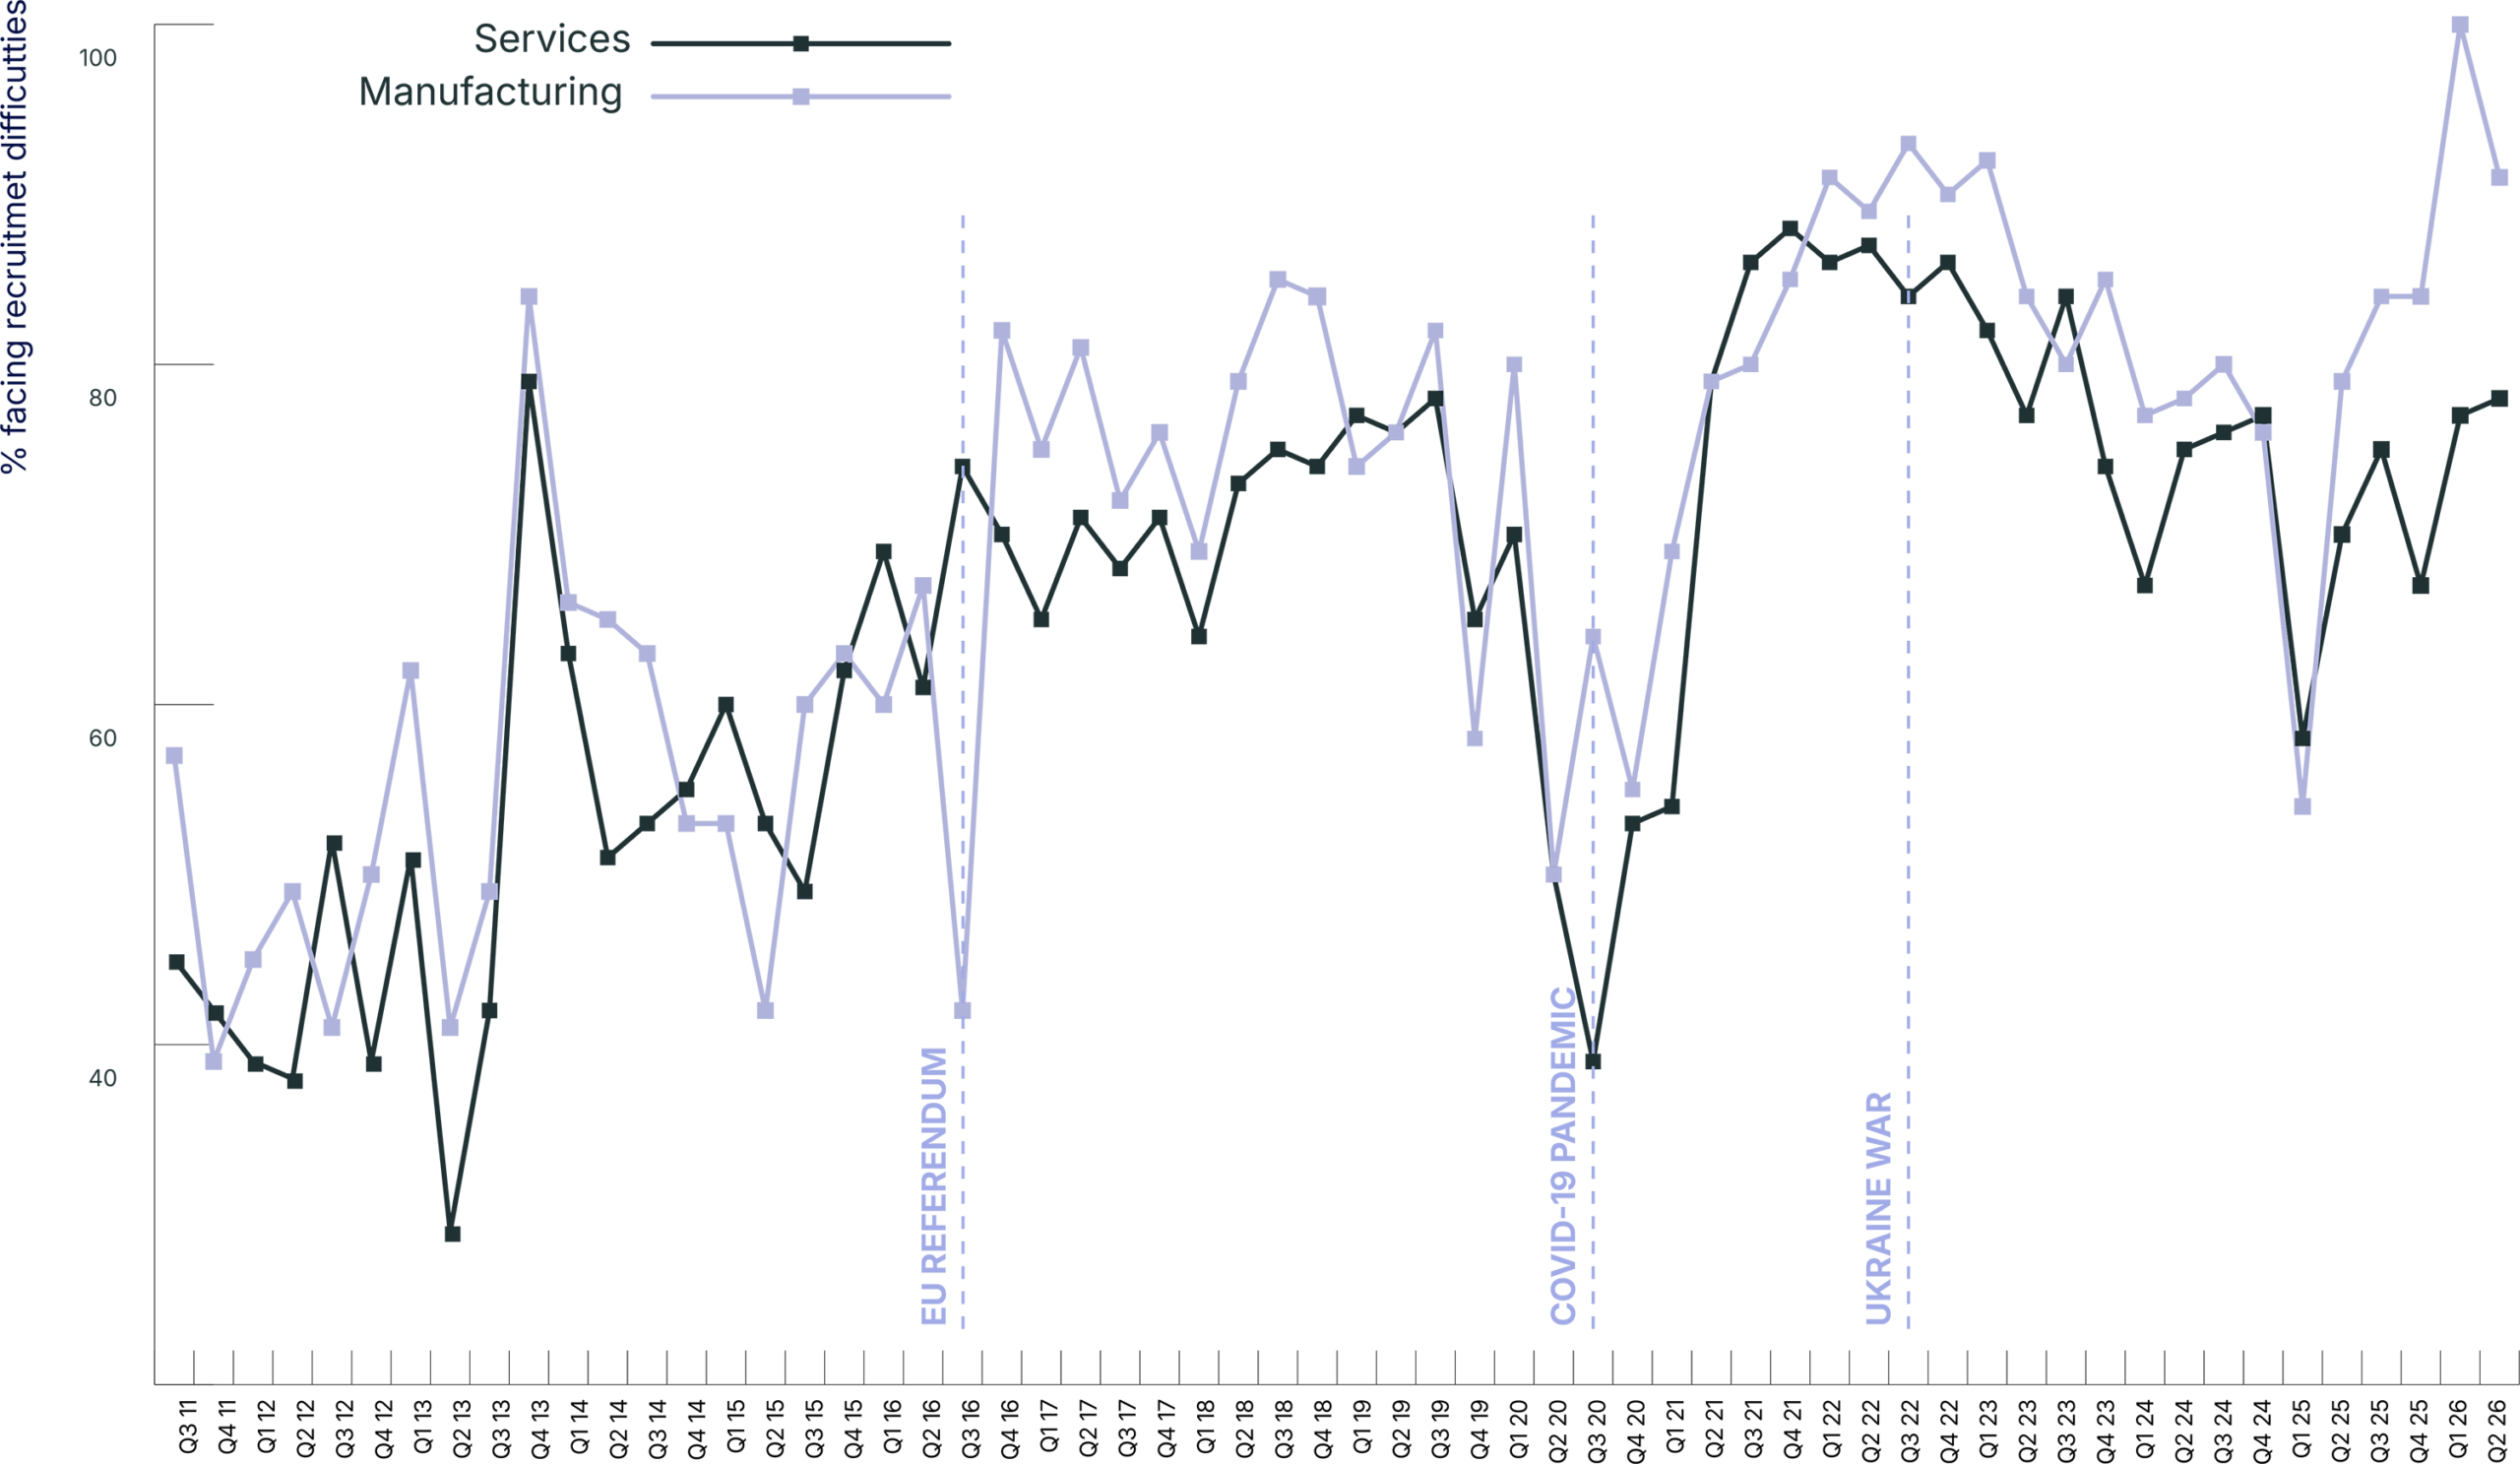
% of firms facing recruitment difficulties
Hiring intentions held up but diverged by sector in Q2 2026, with services balances firming to +29 while manufacturing eased to +20. Both remain only modestly above their pre-pandemic norms and well below the 2021–22 peaks, pointing to steady rather than strong employment growth.
At the same time, a high proportion of firms are actively trying to recruit. Recruitment activity in manufacturing is at or near the highest level recorded in the series at 90%, while services eased slightly to 75% but remained high by historical standards.
However, this is not translating into stronger employment growth. The gap between high recruitment activity and more modest employment expectations reflects hiring for replacement rather than expansion.
Recruitment difficulties remain entrenched. In manufacturing, 91% of firms report difficulty, easing from a peak of 100% in Q1 but still extremely elevated, while services difficulties ticked up to 78%. Both remain far above pre-pandemic norms.
Overall, this points to a labour market where hiring demand remains strong, but supply constraints continue to limit how far that demand converts into employment growth, with Northern Ireland experiencing some of the tightest labour market conditions in the UK.
Confidence and Investment Intentions
Business confidence has diverged in Q2 2026. In services, turnover and profitability expectations have held broadly steady and remain clearly positive. In manufacturing, confidence has weakened materially: turnover confidence fell to +7 and profitability confidence to -5, the latter continuing a decline now running for six consecutive quarters.
While services readings remain comfortably above the lows of 2022–23, manufacturing confidence has fallen back towards those levels, pointing to a fragile and deteriorating outlook in the sector. This weakening is likely amplified by manufacturers’ greater exposure to energy and global cost pressures.
Investment intentions remain positive and ahead of most UK regions, but cautious and volatile. Northern Ireland is among the leading UK regions on both plant and machinery and training investment in both sectors and, more tellingly, these balances are positive in Northern Ireland while running negative nationally, although there is no clear sign of acceleration.
Overall, investment behaviour remains consistent with a cautious environment, with firms continuing to invest but showing no move into a stronger investment cycle, while the divergence in confidence between the two sectors is the defining feature of the quarter.
Cashflow
Cashflow remains one of the weakest indicators in Q2 2026. Conditions are negative in manufacturing (-10) and only marginally positive in services (+7), with the two sectors effectively swapping positions since the previous quarter.
Recent quarters continue to show volatility, with no clear or sustained upward trend. Over the longer run, cashflow has been negative more often than not for both sectors and remains structurally one of the weakest measures in the survey.
Current readings suggest that many firms are operating with limited financial headroom, restricting their capacity to absorb further cost increases or invest for growth, a constraint that is particularly acute in manufacturing this quarter.
Prices and Costs
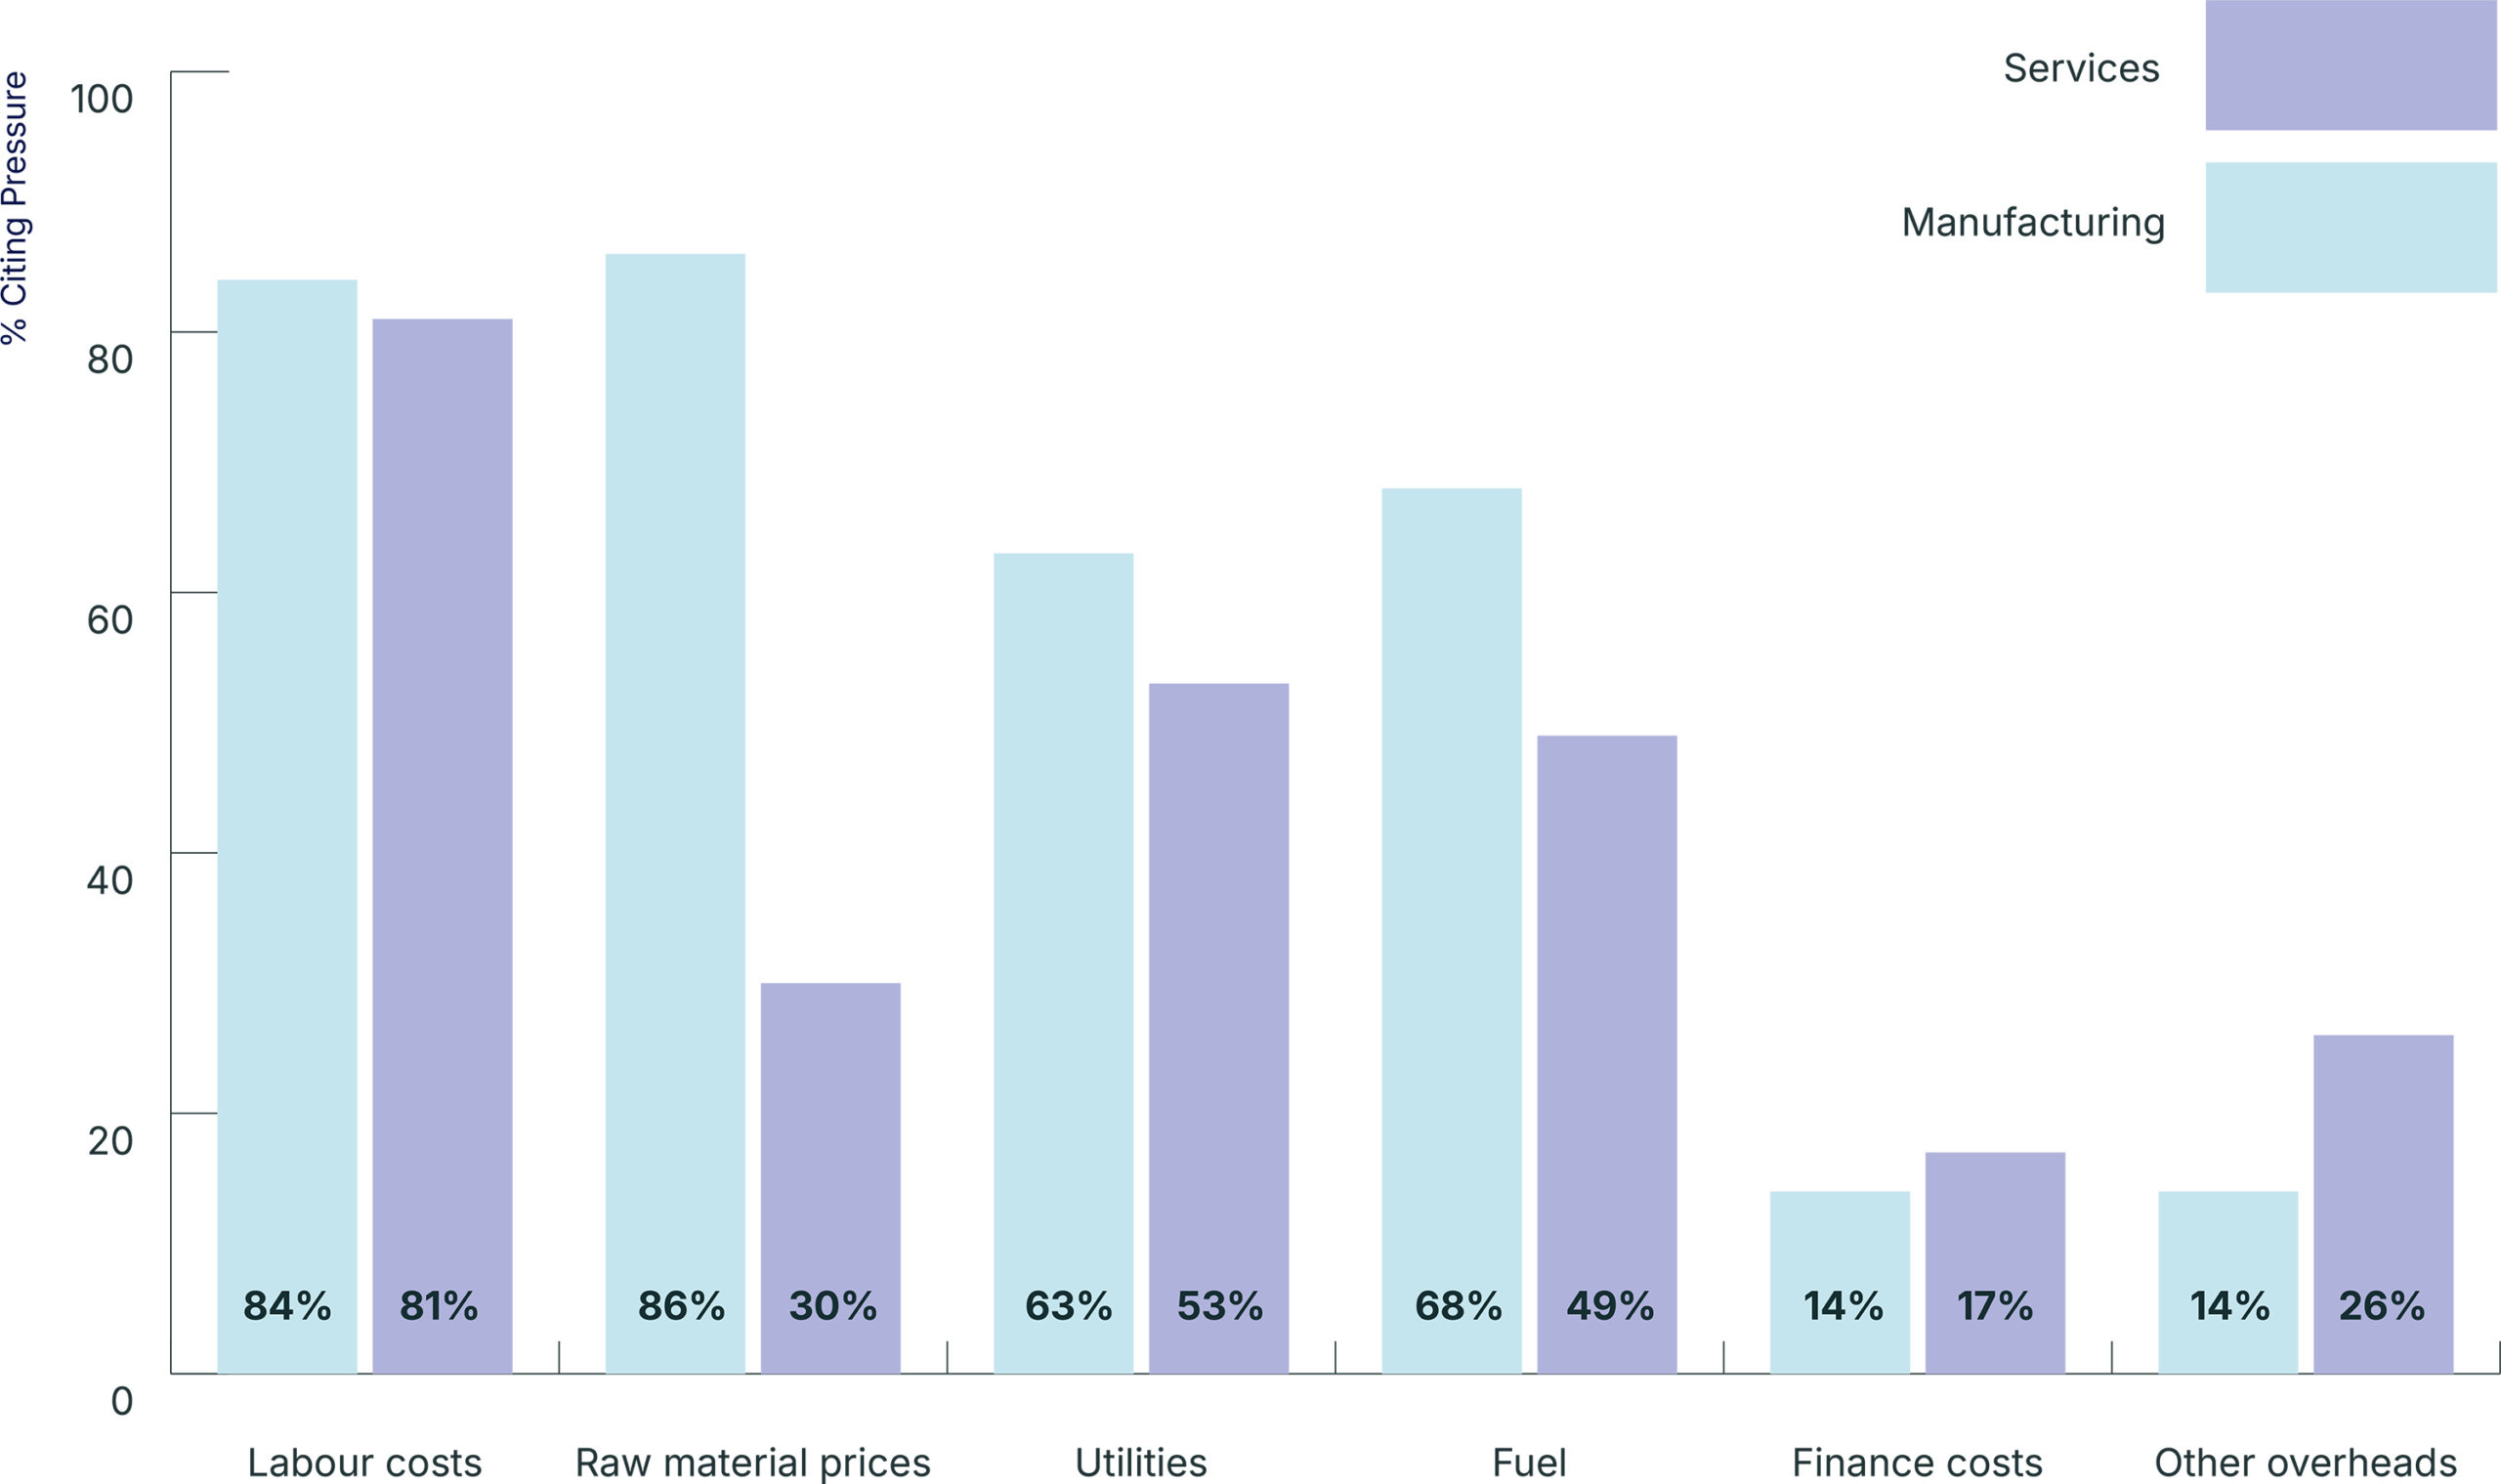
Price pressures remain elevated across both sectors in Q2 2026 and, in manufacturing, have re-intensified. Manufacturing price expectations jumped to +68, their highest in over a year, while services held steady at +49. Both remain far above pre-pandemic norms, though below the 2022 peaks.
The persistence of price increases reflects continued cost pass-through. These pressures are being driven primarily by internal cost factors, with labour costs remaining by far the dominant pressure in both sectors.
Is your business under pressure to raise prices from any of the following? (% citing)
Beyond labour, the cost picture has diverged. In manufacturing, pressures intensified sharply, with raw materials, fuel and utilities all rising. In services, pressures broadly eased, with fuel the main exception. Fuel is the common thread across both sectors, consistent with the wider energy-cost backdrop.
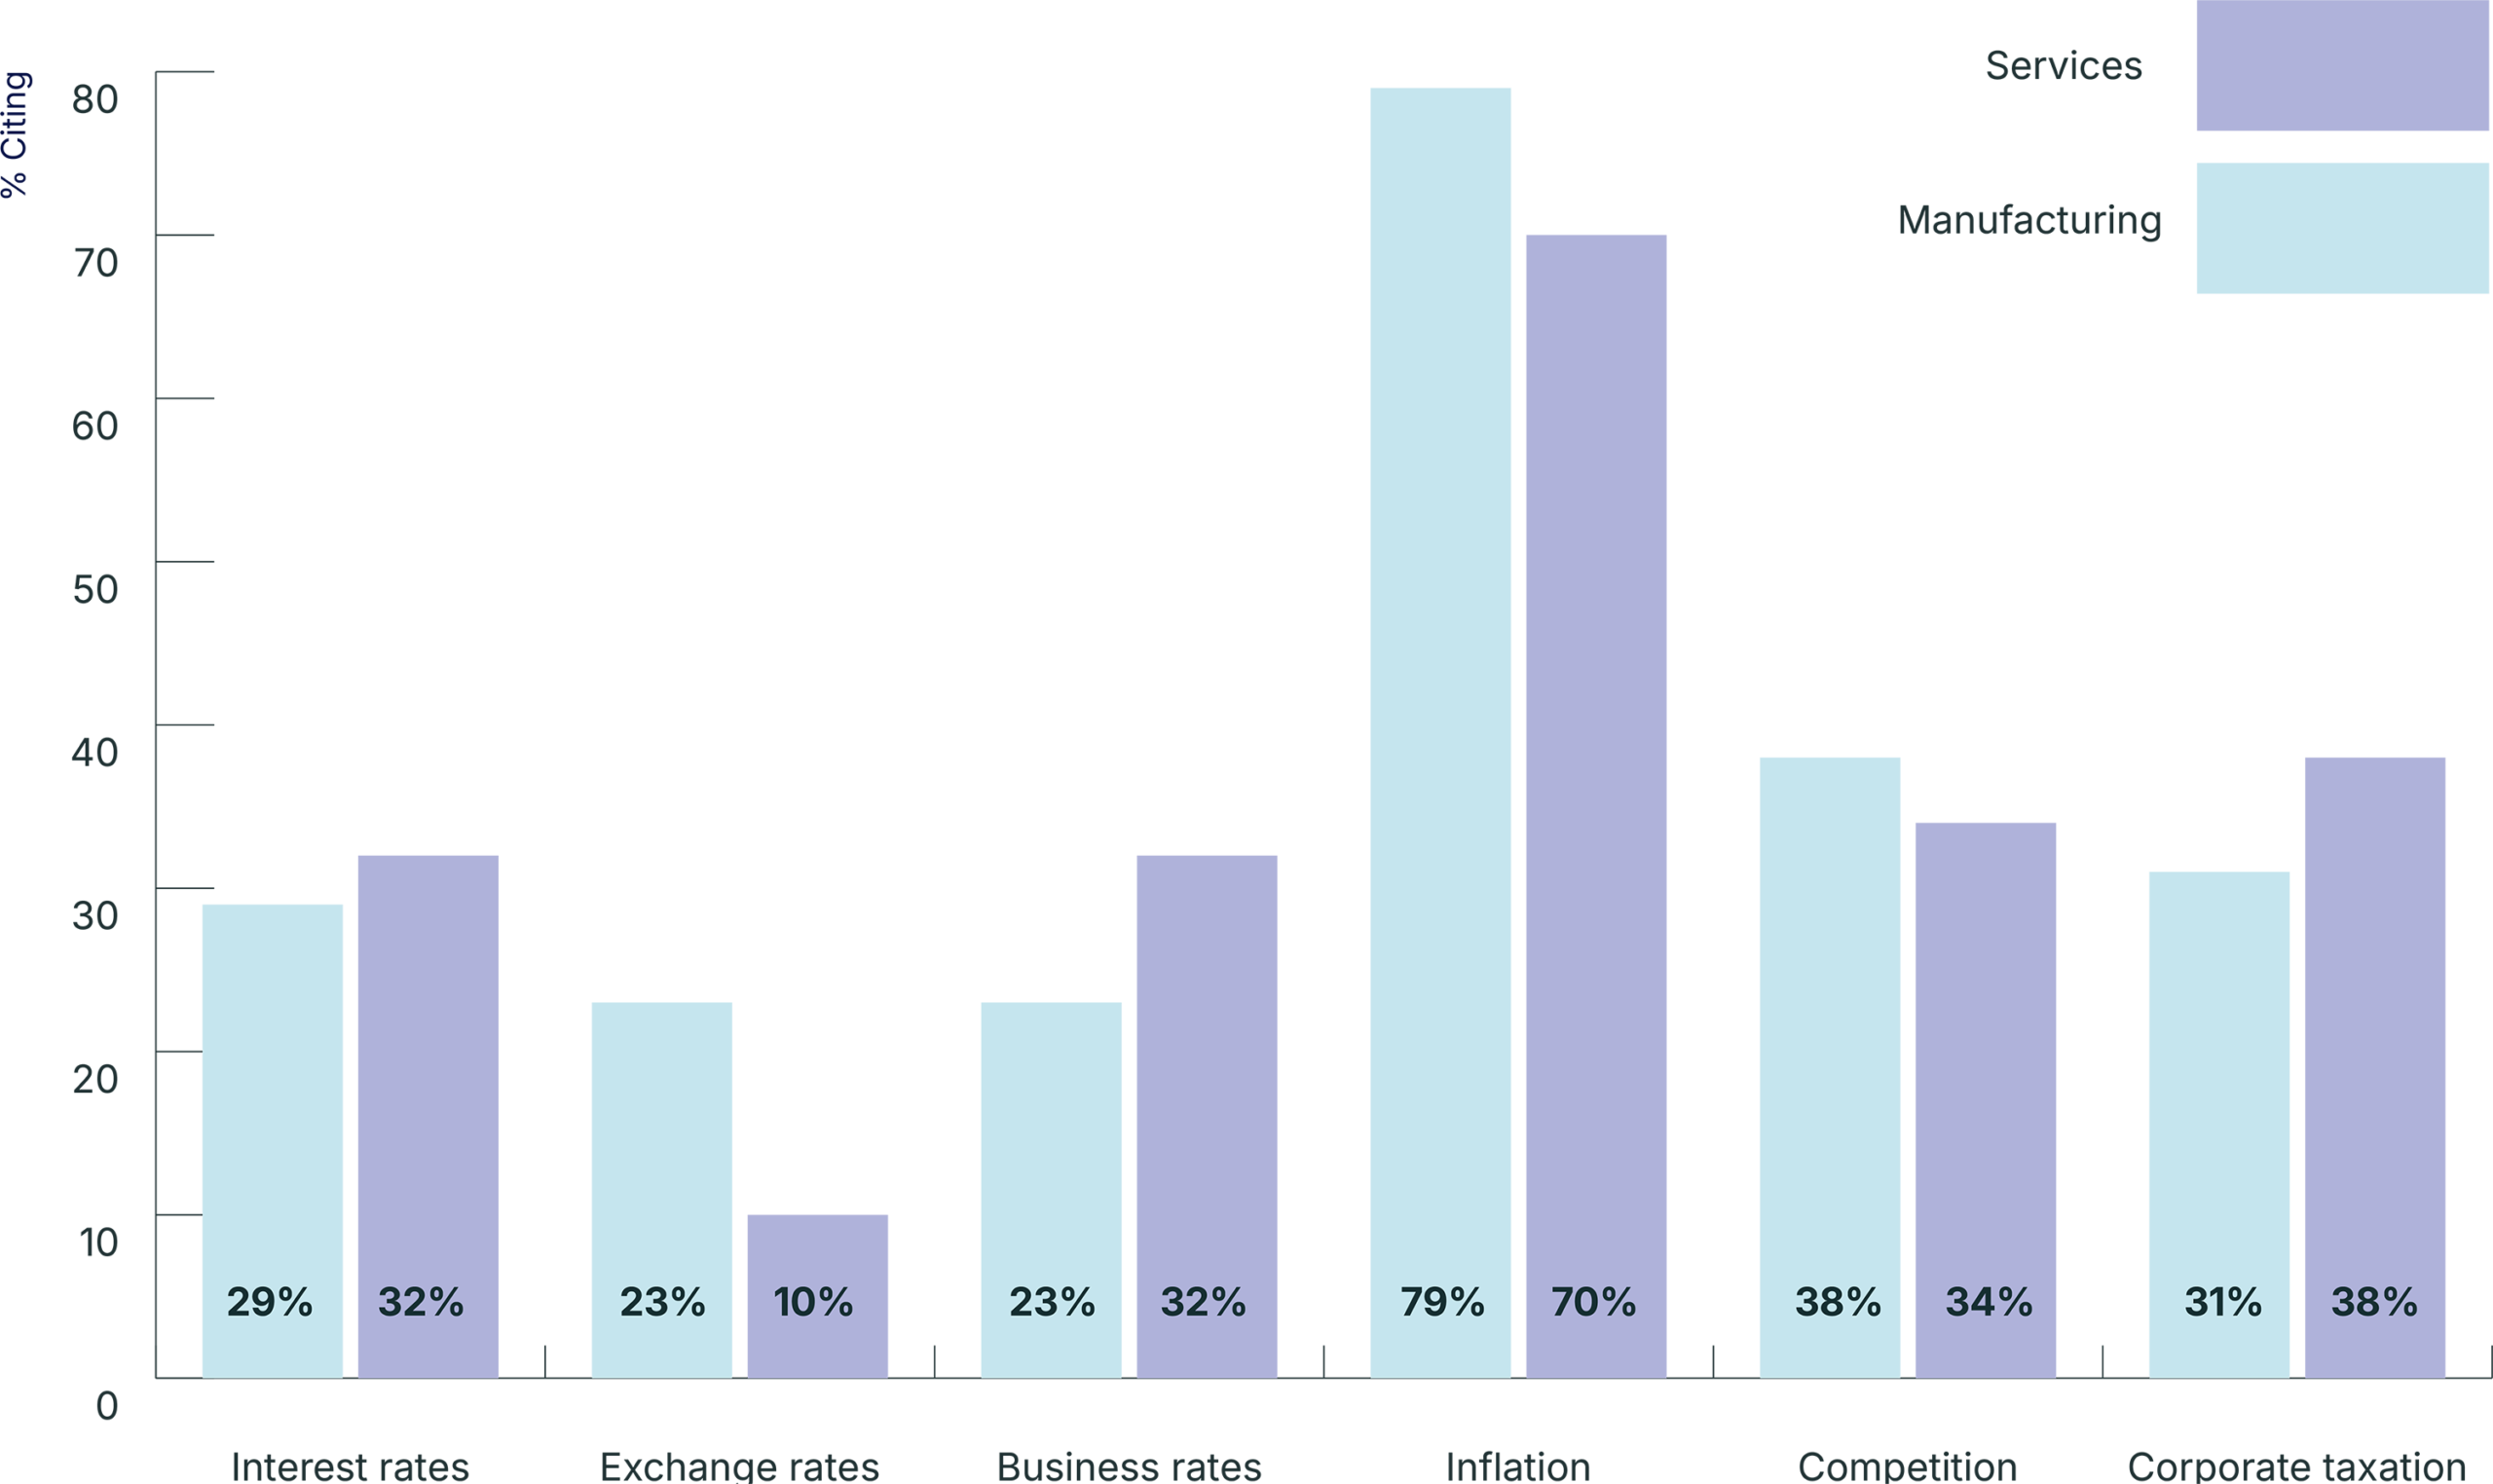
External factors of growing concern (% citing)
External and policy-related concerns have shifted decisively. Inflation has surged to become the single biggest concern in both sectors, cited by 79% of manufacturers and 70% of services firms, overtaking taxation, competition and business rates, all of which eased this quarter.
Taken together, the data point to a renewed environment of elevated and persistent cost pressure, with inflation firmly back at the forefront, led by manufacturing.
Regional Position
Northern Ireland continues to rank strongly across UK regions in Q2 2026, and its relative position has, if anything, strengthened on the activity measures. The clearest standout is investment and jobs: Northern Ireland is among the leading UK regions on both investment measures and on recruitment activity and, more tellingly, these balances are positive in Northern Ireland while negative across the UK as a whole.
In services, performance is particularly strong, with Northern Ireland recording the highest balance of the twelve UK regions on seven indicators: export sales, export orders, employment, recruitment activity, cashflow, and both investment measures. On several of these the margins over other regions are narrow, but three stand clearly apart, with Northern Ireland ahead by a wide margin on investment in plant and machinery, export orders and export sales. In manufacturing, strength is more concentrated, but Northern Ireland still ranks among the leaders on investment and recruitment activity and among the top regions on jobs and exports.
The relative weaknesses are domestic demand and confidence, where Northern Ireland sits closer to the middle or lower end of the regional distribution, and labour availability, where the region reports among the tightest conditions in the UK.
Taken together, Northern Ireland remains one of the strongest-performing UK regions, with its strengths concentrated in investment, hiring and services exports, while trailing on domestic demand and confidence. This reflects resilience and a distinctive export and investment orientation rather than broad-based domestic strength.
Manufacturing
Services
Demand and Confidence
The relative weaknesses are domestic demand and confidence, where Northern Ireland sits closer to the middle or lower end of the regional distribution, and labour availability, where the region reports among the tightest conditions in the UK.
Current Business Conditions
Most firms remain profitable, but often only marginally. Around 83% of firms report trading well or reasonably, with 37% trading well and 46% reasonably. This is broadly in line with recent years and indicates that the majority of businesses remain in positive territory.
At the same time, a significant minority are under pressure: 13% are just covering costs and a further 4% are struggling, meaning around one in six firms (17%) is at best breaking even. The strain falls most heavily on the smallest firms. Just 62% of micro firms (fewer than 10 staff) report trading well or reasonably, against 88% of small firms and 89% of those with 50 or more staff, a gap wide enough to be statistically robust despite the smaller base. Micro firms are also more than three times as likely to be just covering costs or struggling, at 38% against 12% of small firms and 11% of larger ones.
Taken together, the findings point to an economy where most firms remain profitable, but often only just, and where the smallest firms face the greatest strain from weak demand and high costs.
Impact of Iran conflict
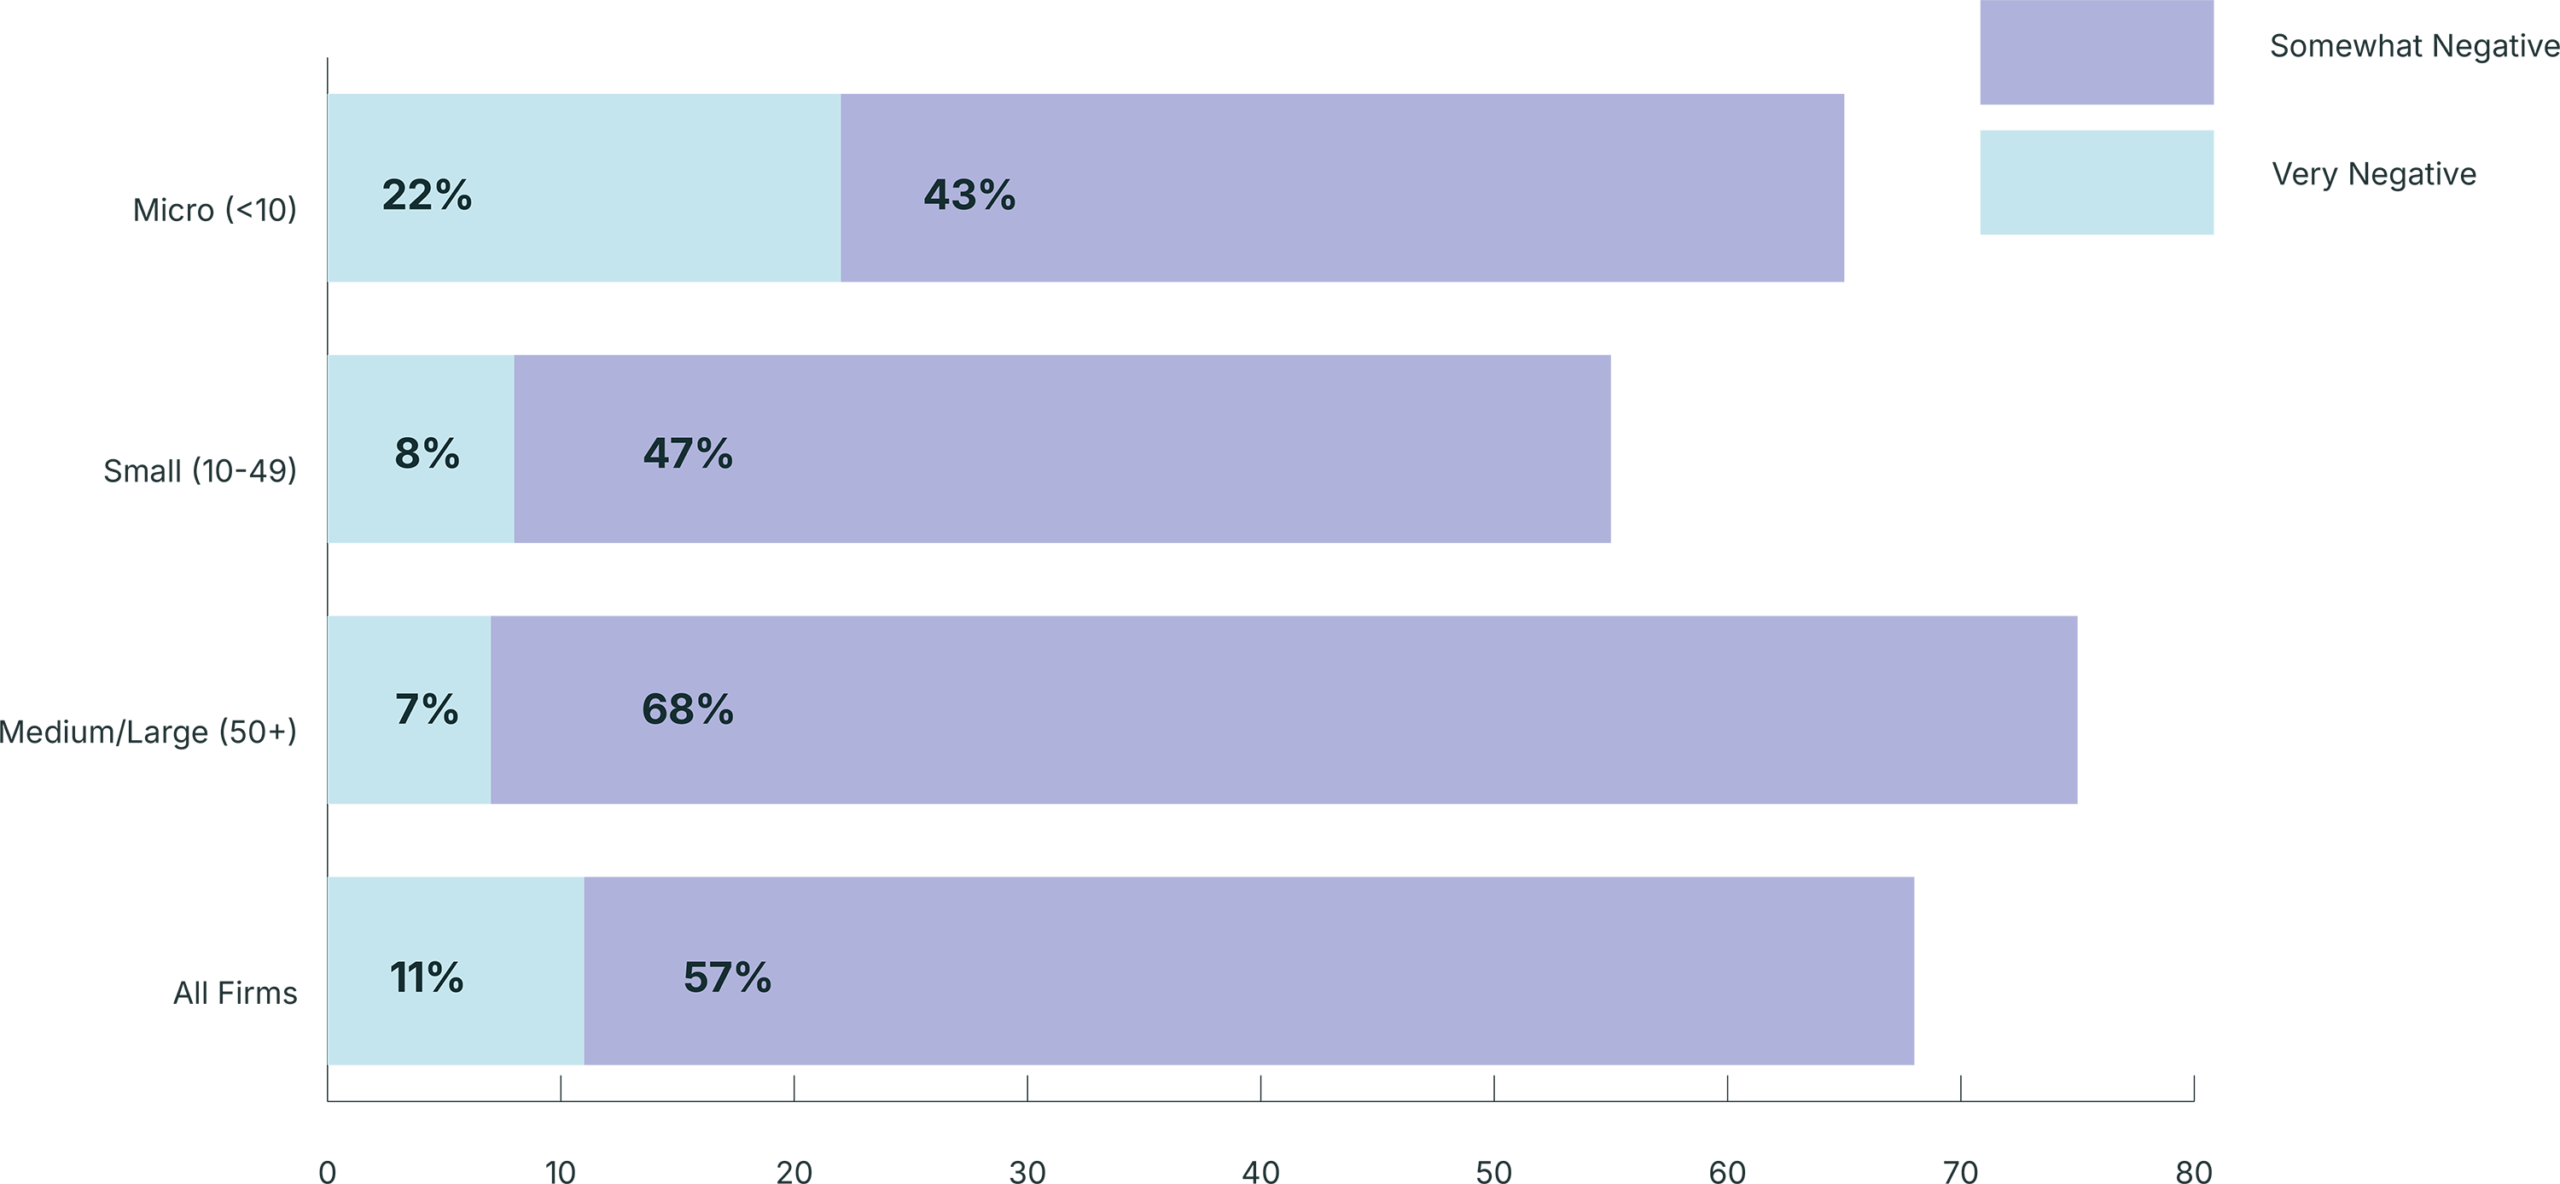
The conflict involving Iran, and the resulting energy and market volatility, has had a clear negative effect on Northern Ireland businesses. Two-thirds of firms (68%*) report a negative short-term impact on their outlook, split between 57% somewhat negative and 11% very negative, while a quarter report no significant impact.
The impact is broad, but its severity falls most heavily on the smallest firms. While larger firms are marginally more likely to report being affected at all, micro firms are far more likely to be hit hard: 22% report a very negative impact, around three times the rate of larger firms. By sector, only manufacturing stands clearly apart, with 82% affected.
*Figures subject to rounding
% of firms reporting a negative impact, by firm size
Which aspects of your business have been, or are expected to be, affected? (% citing)
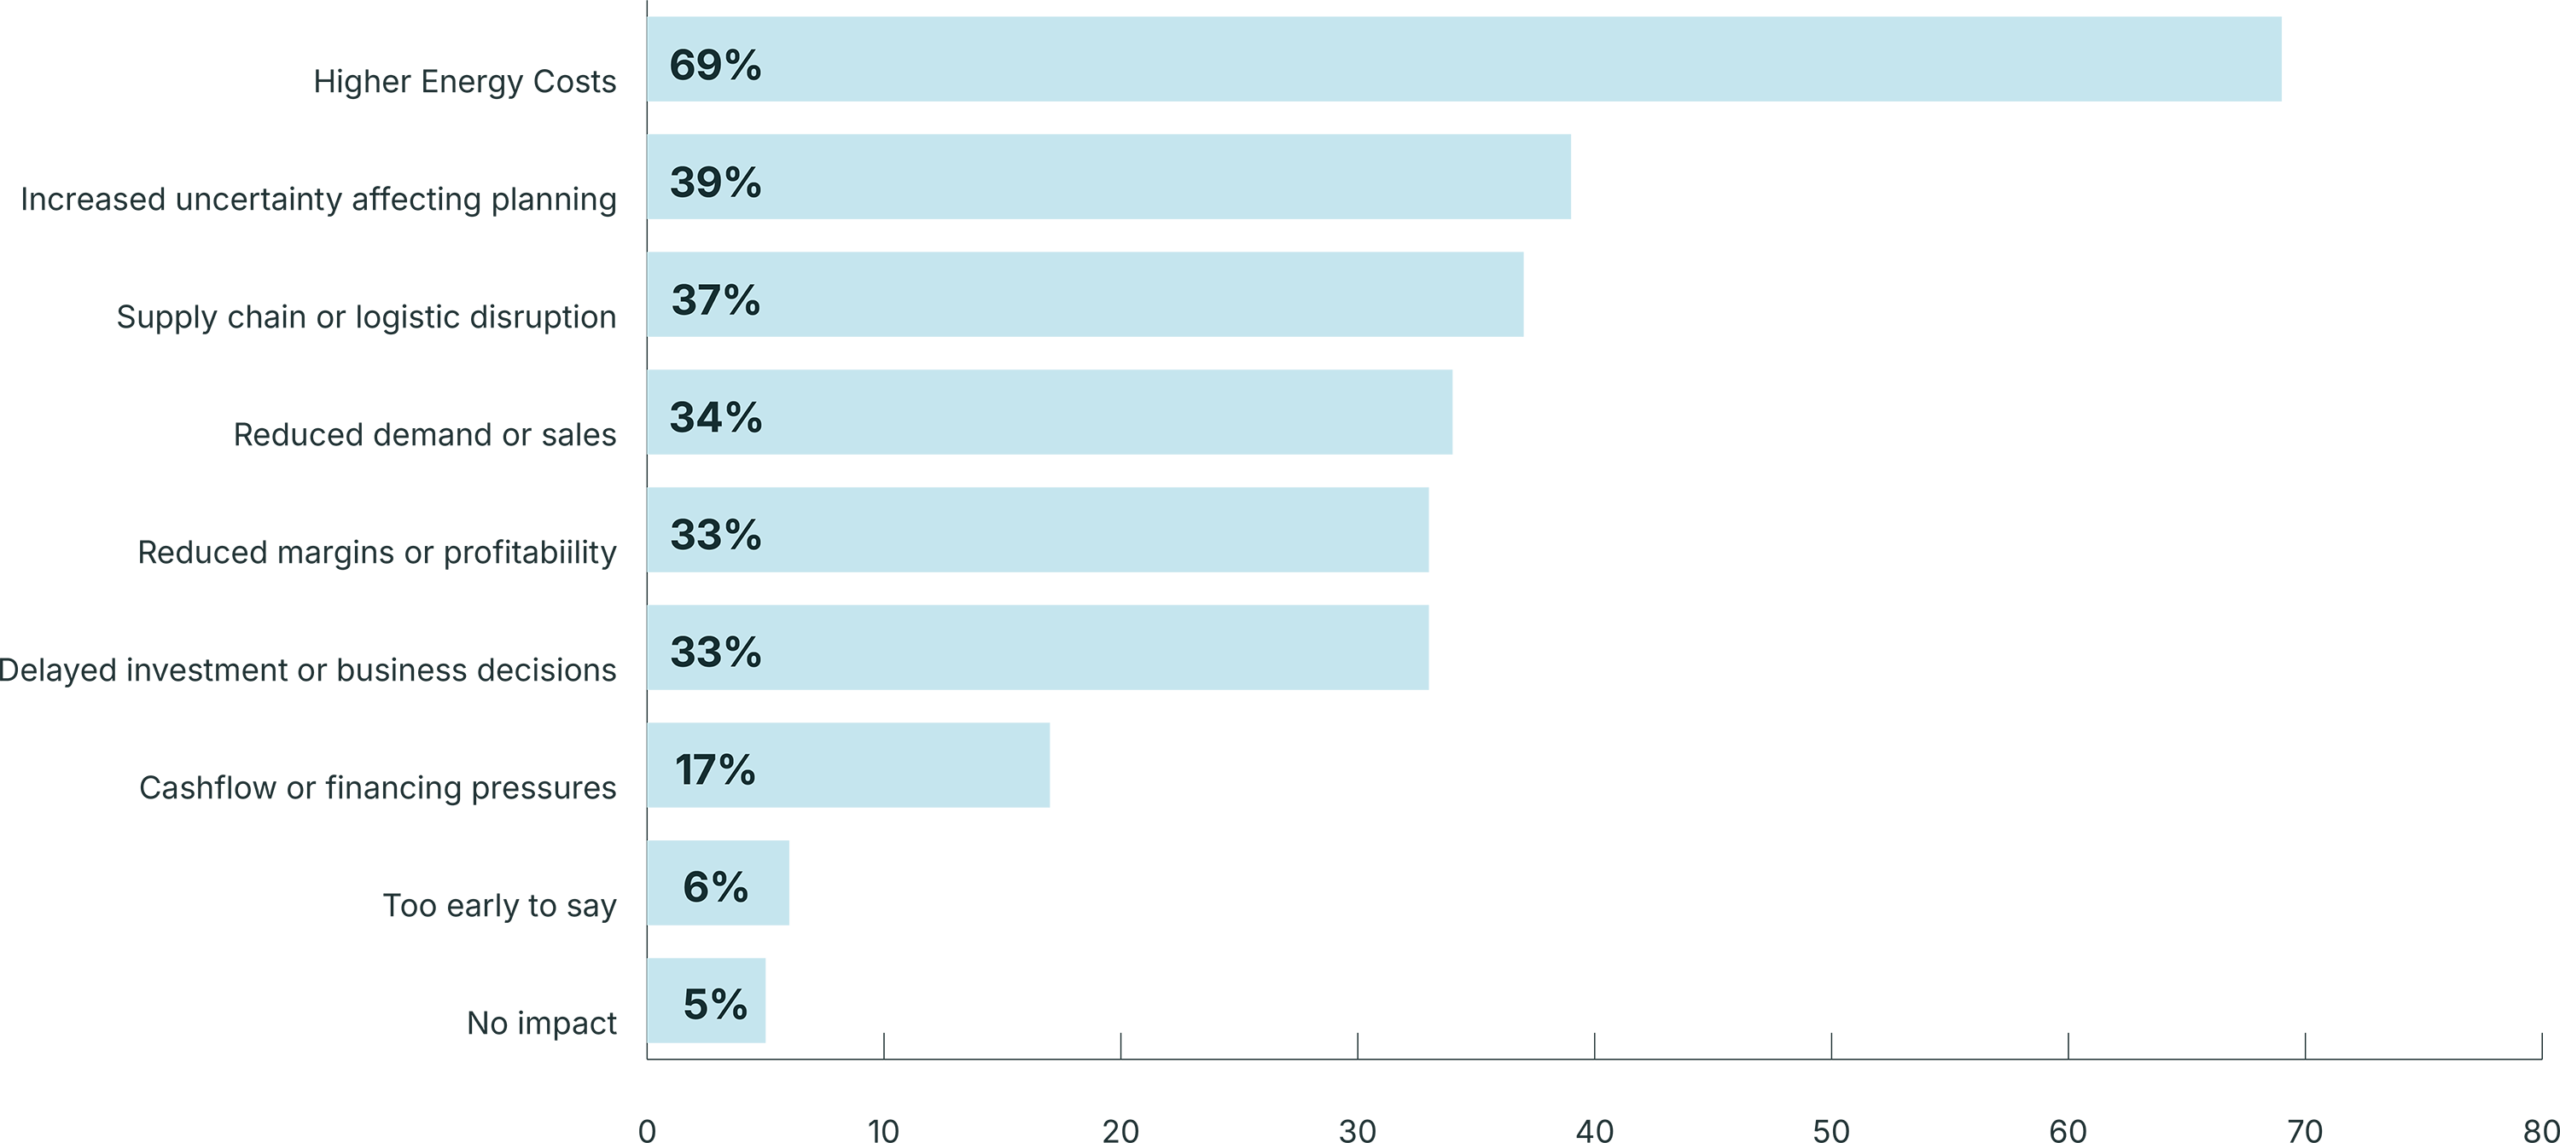
Higher energy, fuel and operating costs are by far the most cited effect, reported by 69% of firms, nearly double any other impact. Increased uncertainty (39%) and supply chain disruption (37%) follow, with reduced demand, margins and investment each cited by around a third. Just 5% report no impact on any aspect of their business.
Most firms are responding, but the response is weighted towards managing costs rather than structural change. Around 77% are taking or considering action: 40% are passing costs on to customers and 34% absorbing them, while a third are cutting spending or delaying hiring. Notably, despite energy being the dominant pressure, just 19% are investing in energy efficiency.
Asked what government should prioritise, businesses point above all to energy. Around four in ten written responses call for direct action on energy costs, falling into three broad types: immediate cost relief, funding for the transition to more efficient and self-generated energy, and a more stable long-term energy supply. Parity with schemes in the Republic of Ireland and Great Britain is a recurring benchmark.
Taken together, the findings show a business base broadly exposed to the conflict through energy and operating costs, with the smallest firms hit hardest, and a clear ask of government centred on energy support.
The QUB Perspective
“The latest survey is something of a mixed bag. Whilst Northern Ireland continues to outperform most of its peers in Great Britain, all 12 UK regions continue to struggle in one form or another. The local economy continues to be buoyed up by the relatively strong economic performance of the Republic of Ireland economy. The latter is helping to offset weak domestic demand conditions particularly within the services sector. External markets continue to support strong service sector activity and confidence looking ahead. Conversely, the manufacturing sector is less optimistic about the challenges ahead.
“In the climate of ‘tariffs on, tariffs off’; and ‘ceasefires on, ceasefires off’; uncertainty remains a given. Meanwhile for both services and manufacturing, skills shortages and cost pressures appear to be switched on permanently.
“On the cost front, ‘Warflation’ is impacting on input costs, notably within commodities and energy. However, much of the newly embedded cost pressures are ‘self-inflicted’, stemming from UK policy as opposed to global factors. Peace in the Middle-East and a re-opening of the Strait of Hormuz will not bring labour costs down. Similarly, UK and NI businesses will continue to face some of the highest electricity costs within Europe. It is the relative cost, rather than the absolute cost, that affects competitiveness.
“In light of the above, the profitability squeeze is set to continue. The latest survey notes that profitability expectations have declined for the sixth successive quarter. Businesses are waiting to see what the new incoming Burnham government will mean for the UK and Northern Ireland. More tax, more devolution? Arguably one of the biggest challenges facing Northern Ireland is delivering on the existing devolutionary arrangements. No agreed multi-year budget, ongoing talks with the Secretary of State and an election looming next year. Unfortunately, we have all seen this movie before.”
Richard Ramsey, Professor of Practice, Queen’s Business School

The NI Chamber Perspective
“Businesses have shown remarkable resilience, but resilience alone is not a strategy for growth. Northern Ireland needs urgent progress on the long-standing barriers to competitiveness, including skills shortages, planning delays, wastewater capacity constraints and energy costs. By addressing these challenges and providing greater certainty for business investment, we can ensure that firms of all sizes are equipped to grow, create jobs and strengthen Northern Ireland’s economic performance in an increasingly uncertain world.”
Suzanne Wylie, Chief Executive, NI Chamber

The QBI survey measures key “balances” across indicators such as local sales, exports, employment, and confidence. The balance equals the percentage reporting an increase minus those reporting a decrease.
A total of 171 businesses responded NI Chamber’s Quarterly Business Insight Survey for Q2 2026, representing more than 52,000 employees in Northern Ireland.
Fieldwork was conducted between 15 May and 8 June 2026.
Helping businesses grow locally and internationally

Helping businesses grow locally and internationally